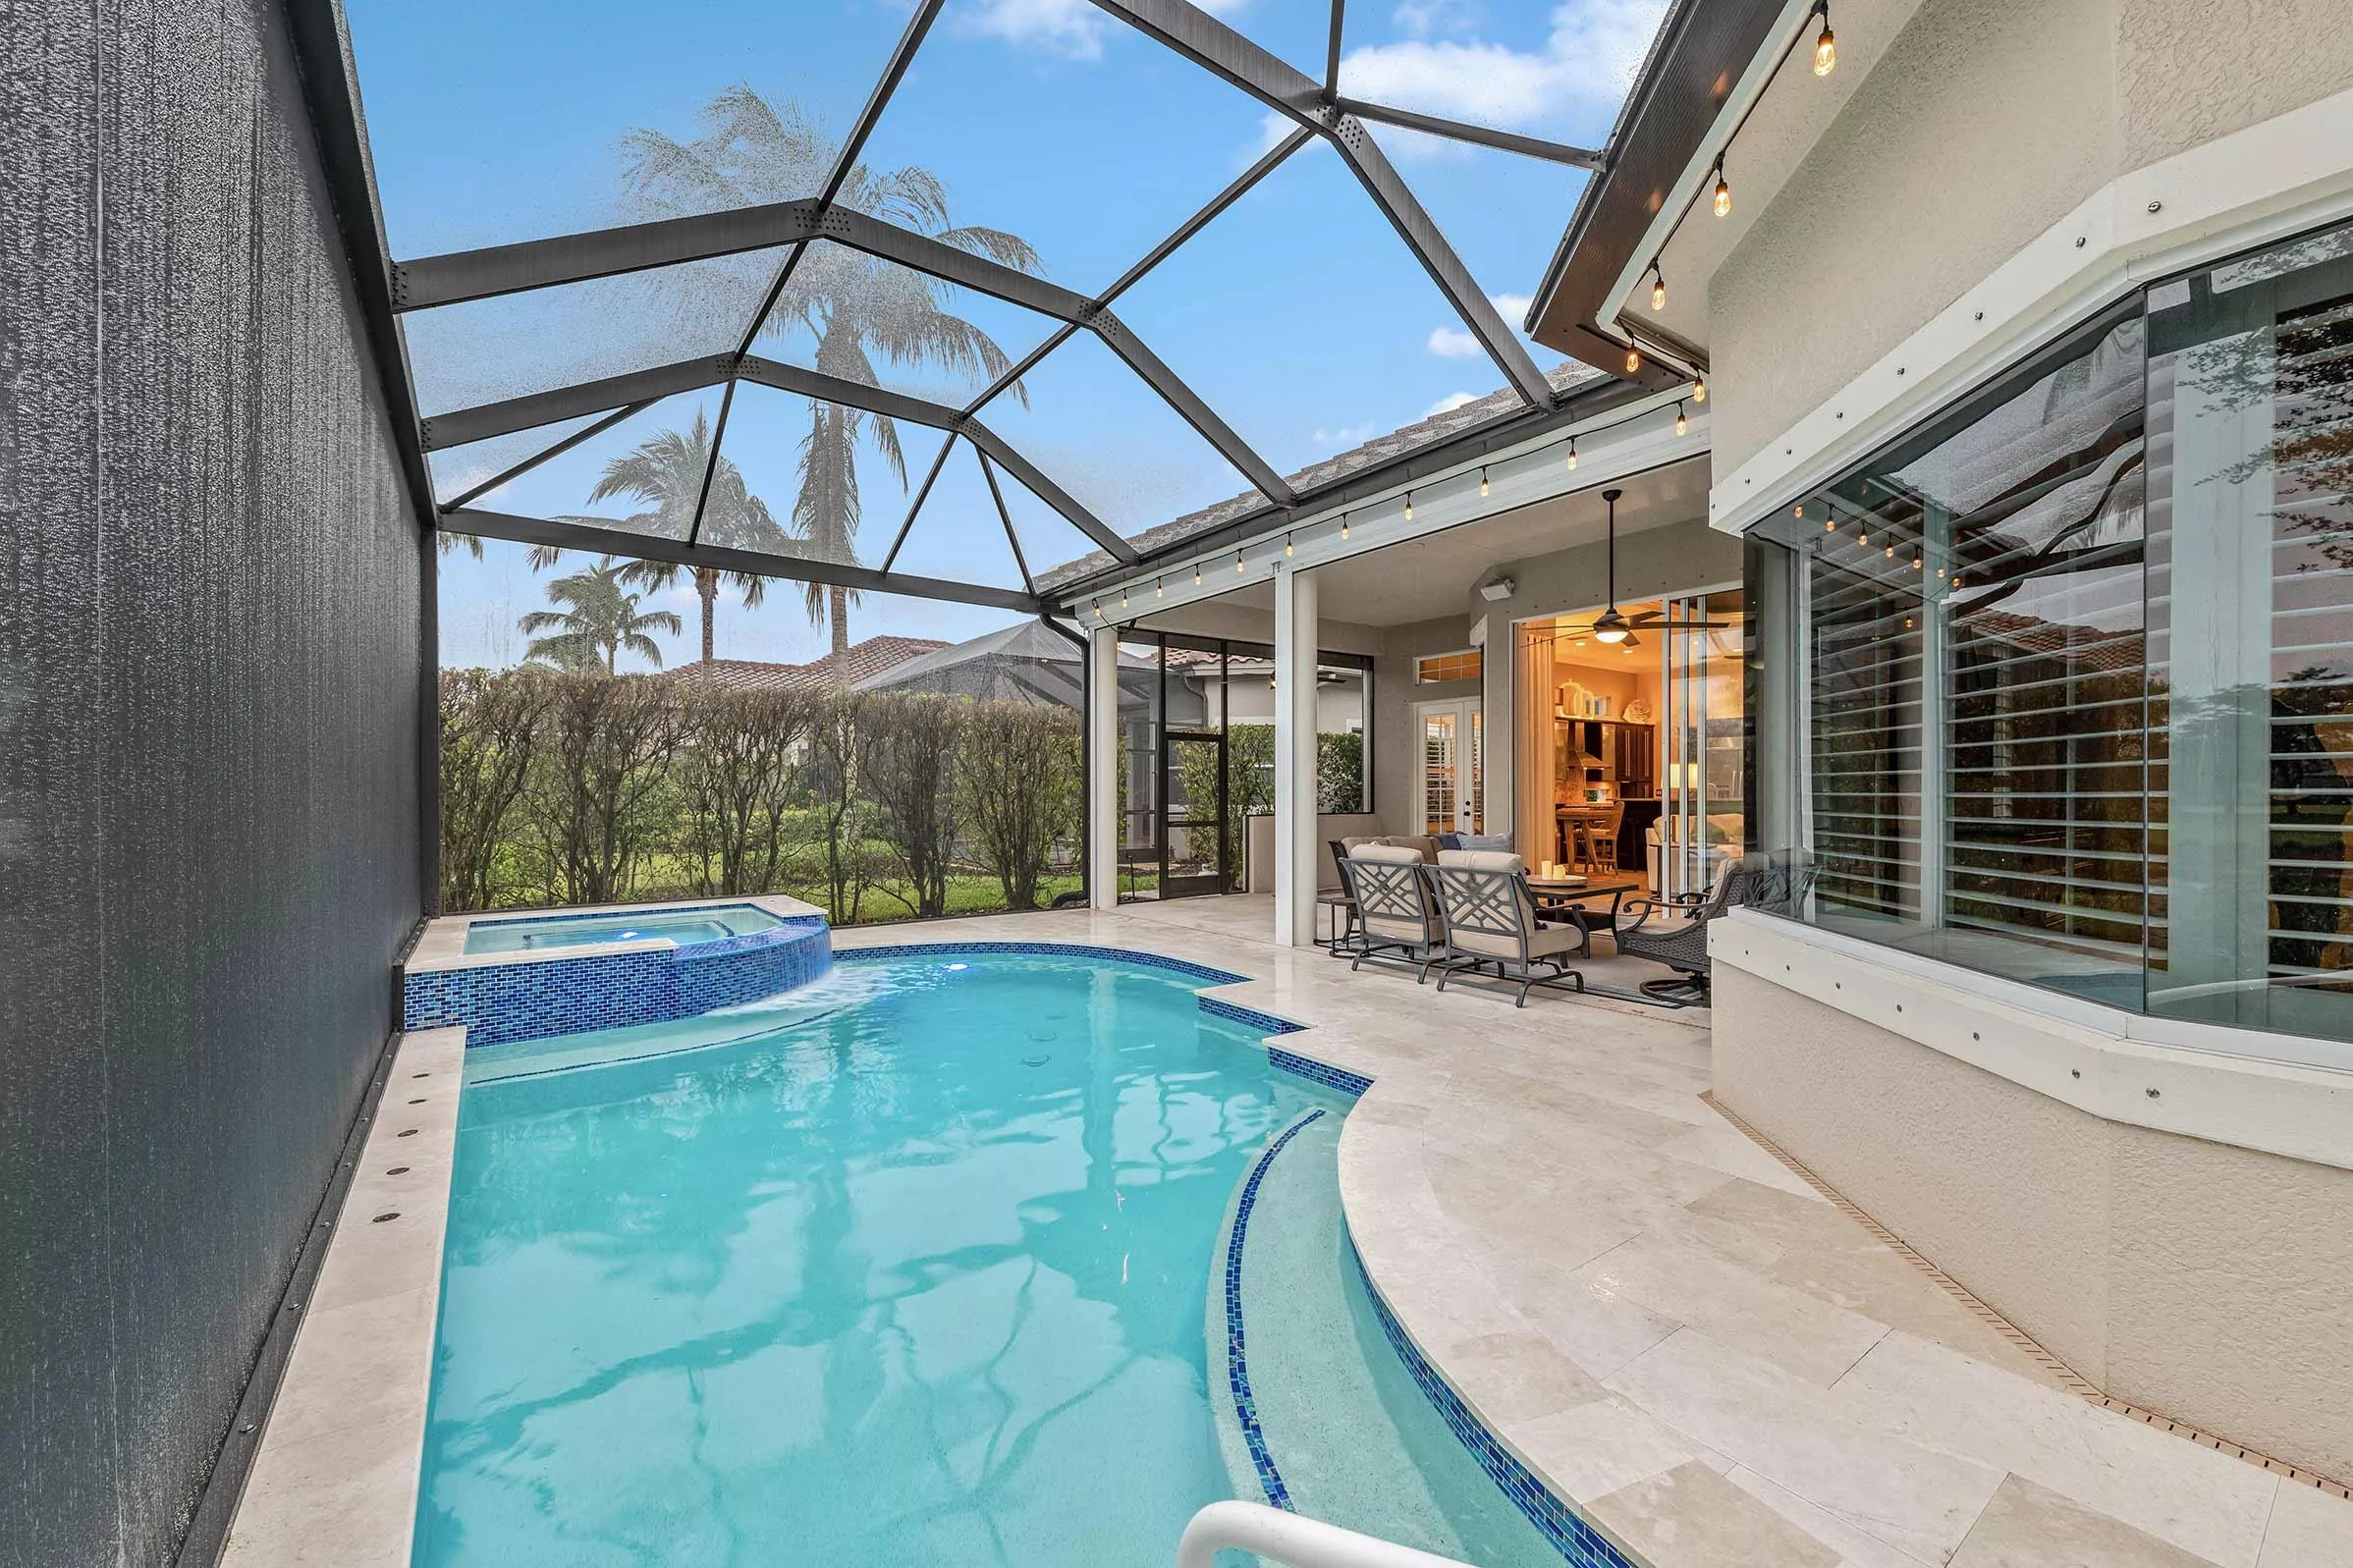
A significant share of our closings at Powers Realty Group, Inc. are all cash transactions, and cash buyers enjoy real advantages: stronger offers, faster closings, and no lender conditions.
But there is one area where cash buyers are quietly at a disadvantage, and almost no one talks about it until it becomes a problem at the closing table: flood insurance.
Many of our buyers have noticed the same pattern. Buyers with mortgages seem to obtain flood insurance easily, while cash buyers find the process slower and more frustrating. Is the system really built to favor the banks? We researched the facts, and the answer is more nuanced than you might think.
Cash buyers are not less insurable. Federal flood insurance through the National Flood Insurance Program (NFIP) is available to any property owner in a participating community, whether or not a mortgage exists. No insurer can deny you an NFIP policy simply because you paid cash.
What cash buyers lose is timing. The entire flood insurance system was designed around mortgage lending, and financed buyers receive a powerful procedural advantage that cash buyers do not: immediate coverage at closing.
Federal law requires flood insurance whenever a property sits in a FEMA designated Special Flood Hazard Area (zones A, AE, AH, AO, V, and VE) and is financed with a federally backed mortgage. That includes FHA and VA loans and any conventional loan sold to Fannie Mae or Freddie Mac, which covers the vast majority of mortgages written in Florida.
This mandatory purchase requirement exists first and foremost to protect the lender's collateral. The bank's investment in your home is at risk in a flood, so federal regulation ensures the coverage is in place before the loan closes and is maintained for the life of the loan.
Because of this, the entire transaction pipeline for a financed purchase has flood insurance built in. The lender orders a flood zone determination. The premium is often escrowed. The insurance agent, the lender, and the title company coordinate so that proof of coverage is in hand before funding. Nobody has to remember to do it. The system does it.
A cash transaction has none of that machinery. No one in the deal is responsible for triggering the flood insurance process. It falls entirely on the buyer, and buyers who do not know the rules often discover them too late.
Here is the single most important fact in this entire discussion.
New NFIP policies normally carry a 30 day waiting period before coverage takes effect. The rule exists to prevent people from buying insurance only when a storm is already on the map.
But there is a major exception: when flood insurance is purchased in connection with the making, increasing, extending, or renewing of a loan, the waiting period is waived entirely. Coverage is effective at loan closing.
Read that carefully. The waiver is tied to the loan, not to the purchase of the home.
A financed buyer walks out of closing with flood coverage in force that day. A cash buyer purchasing the identical policy on the identical house waits 30 days. During hurricane season in Southwest Florida, that is a 30 day window in which your new home is completely uninsured against flood, and standard homeowners insurance will not fill the gap. Homeowners policies exclude rising water and storm surge.
This is why cash buyers perceive flood insurance as harder to get. It is not harder to qualify for. It is harder to have in force when you actually need it.
Florida has a growing private flood insurance market, and it narrows the gap without fully closing it. Private carriers typically use waiting periods of roughly 7 to 15 days, and some offer no waiting period at all in limited circumstances. Notably, several private insurers waive their waiting period only when the coverage is required by a lender, mirroring the NFIP structure.
Private policies can also exceed the NFIP residential limits of $250,000 for the building and $100,000 for contents, which matters in the Naples luxury market where replacement costs routinely run into the millions. Many of our cash buyers ultimately pair or replace NFIP coverage with a private policy for exactly this reason
If your property insurance is written through Citizens Property Insurance Corporation, Florida law now requires flood coverage regardless of how you purchased your home. The requirement has been phasing in since 2024 and applies to all Citizens policyholders by 2027. Cash buyers with Citizens policies are not exempt.
At Powers Realty Group, Inc., we guide our cash buyers through this process well before closing. The strategy is simple:
The perception that mortgage buyers get flood insurance more easily than cash buyers is grounded in fact, but the reason is procedural, not discriminatory. The lender's need to protect its investment created a federal framework in which financed buyers receive instant coverage and built in coordination, while cash buyers must navigate the process alone and wait out the 30 day clock.
The good news: with the right guidance and a little lead time, a cash buyer can close in Naples just as protected as any financed buyer. That guidance is part of what we do every day.
Thinking about a cash purchase in Naples or Marco Island? Contact Powers Realty Group, Inc. at our Fifth Avenue South office and let our team help you close with confidence, coverage included.
This article is provided for general informational purposes and reflects publicly available information about the National Flood Insurance Program and Florida insurance requirements. It is not insurance, legal, or financial advice. Please consult a licensed Florida insurance professional regarding your specific property and coverage needs.
Powers Realty Group, Inc. 780 Fifth Avenue South, Naples, FL Milwaukee's Luxury Leader | Wisconsin's #1 Boutique Broker™
Yes. NFIP flood insurance is available to any property owner in a participating community, with or without a mortgage. Cash buyers cannot be denied a policy for lacking a loan, but they are subject to the standard 30 day waiting period before coverage takes effect.
Federal rules waive the NFIP's 30 day waiting period when flood insurance is purchased in connection with a loan, so financed buyers have coverage effective at closing. The waiver is tied to the loan itself, so cash purchases do not qualify and coverage begins 30 days after purchase.
Generally no. The federal mandatory purchase requirement applies only to federally backed mortgages on homes in Special Flood Hazard Areas. However, Citizens Property Insurance policyholders must carry flood coverage under Florida's phased mandate, and flood insurance is strongly recommended for all Florida properties.
Apply for NFIP coverage at least 30 days before closing so the policy is effective at or near possession, or obtain a private flood policy, which typically carries a shorter waiting period of roughly 7 to 15 days and can offer higher limits suited to luxury properties.
No. Standard homeowners policies exclude damage from rising water and storm surge. Flood insurance is a separate policy, and in Southwest Florida most homeowners need both.

Recent Blog Posts on Real Estate Perspectives
Naple Real Estate Perspectives
September 29, 2026 | Suzanne Powers | Powers Realty Group, Inc.
Selling Your Isles of Collier Home? Why Gretchen Keating Is the Agent to Call
Naple Real Estate Perspectives
September 28, 2026 | Suzanne Powers | Powers Realty Group, Inc.

Naple Real Estate Perspectives
September 21, 2026 | Suzanne Powers | Powers Realty Group, Inc.
Living in the Isles of Collier Preserve: HOA Fees, Neighborhoods, and What Life Is Really Like
Powers Realty Group, Inc. is a distinctive boutique real estate broker focused on the needs of customers delivering exceptional results. We are Florida's Gulf Coast experts. Call us at 239.682.7476 about buying or selling your home.

Powers Realty Group, Inc. - Naples / Marco Island
780 Fifth Avenue South, Suite #200
Naples, FL 34102
239.682.7476
Powers Realty Group, Inc. - Shorewood
4214 North Oakland Avenue
Shorewood, WI 53211
414.963.0000


